The final walkthrough is your last look at the home, usually within a few days of closing, to confirm that agreed repairs were completed and the property is in substantially the same condition as when you went under contract. It is not a second inspection and not a chance to renegotiate the price. It is the moment to catch problems while the seller still has a reason to fix them.
What your contract says
The standard resale purchase contract published by the Arizona Association of REALTORS gives the buyer reasonable access to walk through the property for two purposes: to confirm that agreed corrections and repairs were done, and to confirm the premises are in substantially the same condition as on the date the contract was accepted. Builder contracts and custom contracts can read differently, so check your own.
When to schedule it
Aim for one to three days before close of escrow, and after the seller has moved out if possible. An empty house hides nothing: you can see the floors under the rugs and the wall behind the couch.
Remember how closing works in Arizona. You usually sign a day or two before the sale is final, and the sale closes when the deed records with the county. Walk the home before that happens, not after. See Closing Day in Arizona.
The utilities must be on. You cannot test an air conditioner or a water heater in a house with the power and gas shut off.
What to bring
- Your inspection report and the signed repair agreement.
- Receipts or invoices for the repairs the seller agreed to make.
- The contract's list of items that stay with the home.
- A phone charger to test outlets.
- Your agent.
What to test
Repairs. Check every item on the repair agreement against the receipts. Licensed contractor work should come with an invoice, not a verbal assurance.
Systems.
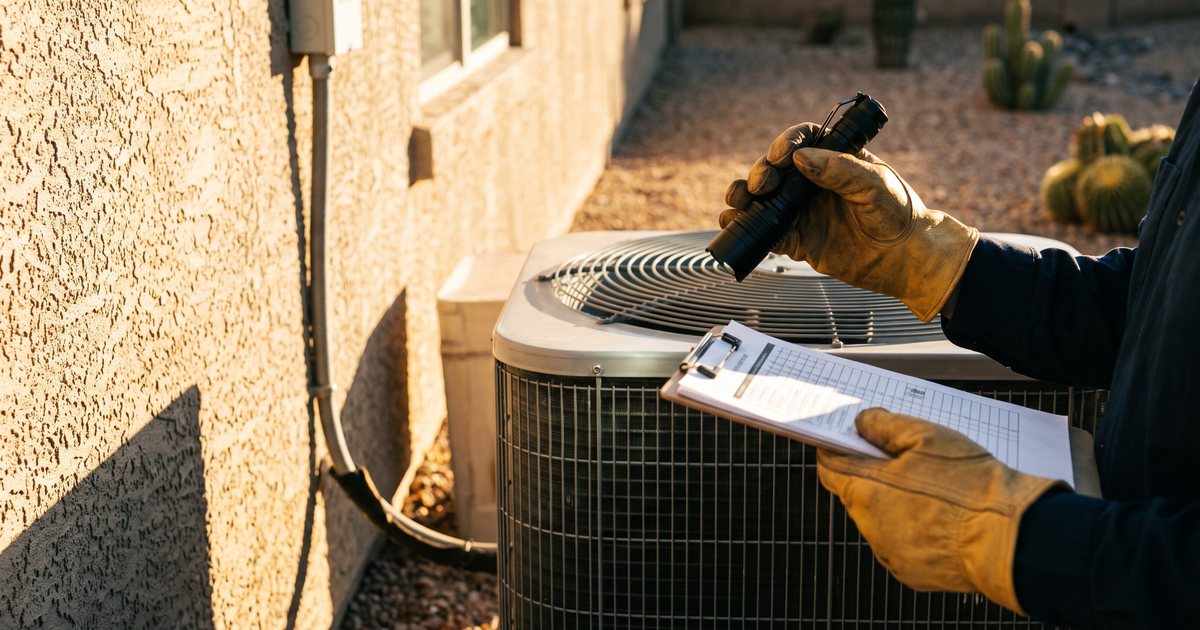
- Run the air conditioning and the heat, each for several minutes. In an Arizona summer this is the one you cannot skip.
- Run hot water at a faucet and flush every toilet.
- Turn on each appliance that conveys with the home.
- Open and close the garage door and count the remotes.
- Check the pool equipment is running and the water is clear.
- Run the irrigation timer through a zone or two.
- Flip the lights and ceiling fans. Open and lock the windows and doors.
Condition.
- Look for new damage from the move: gouged floors, dented walls, a cracked tile.
- After a monsoon storm, check ceilings for fresh water stains.
- Look in the garage, the attic access and the yard for debris and leftover paint or chemicals.
Items that stay. Appliances, window coverings, mounted fixtures, the mailbox key, pool equipment and anything else the contract lists. If the home has solar, confirm the transfer paperwork is in process.
If something is wrong
Tell your agent before you leave the property. Then choose from the options below, in writing.
- The seller fixes it before closing. Best when the fix is quick and can be verified.
- A credit or price change by addendum. Your lender has to approve it, and a change in the numbers can require a revised Closing Disclosure.
- A repair holdback in escrow. Money is set aside until the work is done. Not every loan program allows it, so ask your loan officer first.
- Move the closing date. Both sides agree in writing. Check your rate lock expiration before you agree to any delay. See Rate Lock vs Float.
- The contract's notice process. The Arizona contract has a formal way to notify the other party of an unmet obligation. Your agent or a real estate attorney handles that.
Do not close on a verbal promise. Once the deed records, your leverage is gone and you are left with a claim to pursue instead of a repair to receive.
What your lender needs to know
If the home was damaged after the appraisal, by a fire, a flood, a roof failure or a break-in, tell your loan officer the same day. The lender may require the damage to be repaired and inspected before funding. Your homeowners insurance also has to be active on the day of closing. See Homeowners Insurance and Your Mortgage.
New construction is different
With a builder, the walkthrough is usually an orientation with a punch list. Items are marked, the builder commits to dates, and some work is completed after closing under the builder's warranty. Get the list and the dates in writing, and ask how warranty requests are submitted. Many buyers also hire an independent inspector before this meeting. See What Does a Home Inspection Cover?.
A ten-minute version if you are short on time
- Repairs match the receipts.
- Air conditioning cools and the heat works.
- Hot water, toilets, appliances.
- Garage door, remotes, keys.
- No new damage, no debris.
- Everything on the stays-with-the-home list is still there.
After the walkthrough, the next date to know is your first payment. See When Is My First Mortgage Payment Due?.
Why ask me
- I answer the question before I sell you anything. If renting, waiting or a different program is the better move, I will say so.
- Real numbers, not a calculator guess. I price your actual scenario, side by side, with the fees on the page.
- Every program under one roof. Conventional, FHA, VA, jumbo, and non-QM options like bank statement, DSCR and asset-based loans, so the program fits you instead of the other way around.
- You talk to the principal. Ricky Khamis is President of EPiQ Lending, NMLS #173141, lending in Arizona since 1999 and a 2025 Presidents Club Winner at CMG Home Loans. Direct line: (480) 999-9842.
EPiQ Lending is NMLS #1936984, at 7975 N. Hayden Road, Suite A-101 in Scottsdale. Verify all of it before you trust any of it: Ricky's EPiQ Lending profile, the Scottsdale branch, and the license itself at NMLS Consumer Access. Hold every lender to that standard, including us.
More plain-English answers in the Mortgage Education library.
Equal Housing Opportunity. This is general information, not a commitment to lend or an offer to extend credit. Program guidelines, eligibility requirements and documentation standards vary by investor and change over time. Rates, terms and program guidelines change and depend on credit approval, property appraisal and other qualifying factors. Not all applicants will qualify. This is not legal or tax advice; consult a qualified professional about your own situation.
Find out which program actually costs you less
FHA, conventional and jumbo price the same borrower very differently once the mortgage insurance is compared across the years you will own the home. Tell me the shape of your file and I will run them side by side.
Looking at a specific home? Send me the address and I will run the numbers: rickykhamis.com/analyze